🔵 EG LRM-14: Weekly Market Liquidity Audit Report | May 7, 2026

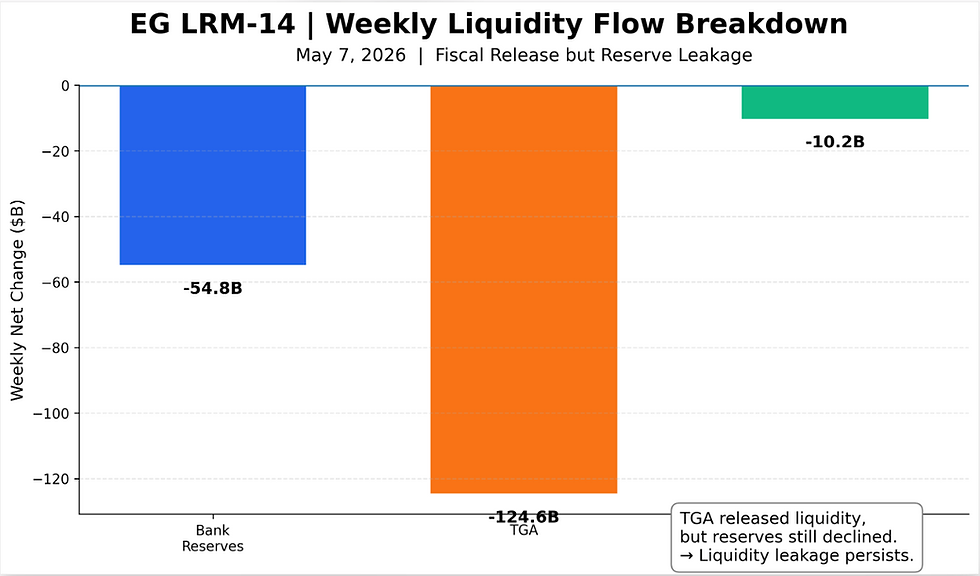
EG LRM-14 | Weekly Liquidity Flow Breakdown, Fiscal Release but Reserve Leakage
🔵 EG LRM-14: Weekly Market Liquidity Audit Report | May 7, 2026
🔵 Liquidity Regime: Abundant
🟡 Status: Re-calibration Under Pressure
🟠 Condition: Fiscal Release, but Reserve Leakage
🔴 Risk Coefficient: Moderate
This week’s H.4.1 data revealed a structurally important divergence beneath the surface.
While the Treasury General Account (TGA) declined sharply — theoretically releasing liquidity back into the system — bank reserves still fell by nearly $55B.
That is the key signal.
Normally:
TGA ↓ → Reserves ↑
But this week:
TGA ↓ → Reserves ↓
Meaning:
Liquidity was released fiscally, but failed to remain inside the banking reserve system.
Core Ledger Extraction (Unit: $B)
• Bank Reserves: $2,864.2B (-54.8B WoW)
• TGA: $857.3B (-124.6B WoW)
• ON RRP: $312.5B (-10.2B WoW)
EG LRM-14: Weekly Market Liquidity Audit Report Interpretation:
The market is no longer facing a classic fiscal drain phase.
Instead, the system appears to be entering a “liquidity redistribution” phase, where released liquidity leaks through other balance-sheet channels rather than reinforcing reserve balances.
This is not a scarcity regime yet.
Bank reserves remain near the critical ~$3T zone, and systemic liquidity is still broadly abundant.
However, the cushion is becoming thinner.
Implications:
• Risk assets can continue advancing• But liquidity support is less expansionary than earlier in the year• Market continuation increasingly depends on earnings dispersion, positioning, and sector rotation rather than broad liquidity acceleration• Future Treasury issuance and reserve management operations now matter more because ON RRP is no longer a meaningful shock absorber
Bottom Line:
Liquidity is still abundant.
But the transmission mechanism is weakening.
That shifts the market from “easy liquidity expansion” toward a more selective and friction-sensitive phase.
Founder's notes
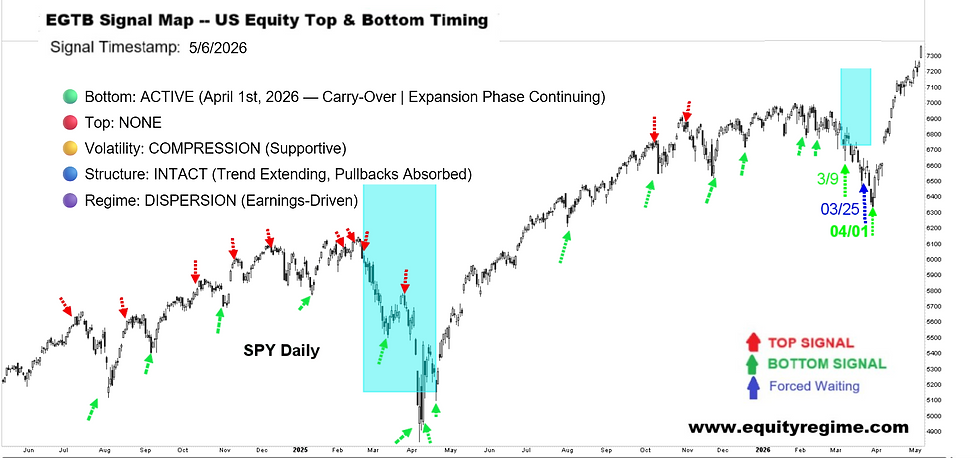
Today’s pullback looked much more like rotation fatigue than structural deterioration.
$SPY closed down just 0.31%, but higher-beta AI leadership took a sharper hit:$SMH -1.75%$AMD -3%+$AMAT -4.19%
And yet the latest AAII data shows something important beneath the surface:
Bears dropped sharply from 39.7% to 33.0%, while neutral sentiment surged to 28.7%.
That is not euphoric positioning.
That is a market where recently-converted bulls are still waiting for their first “good dip” to buy.
Even today’s EGLRM-14 liquidity update supports that interpretation.
Yes, reserve balances weakened and liquidity transmission is becoming less efficient —but systemic liquidity is still broadly abundant, not restrictive.
In late-stage tops, pullbacks create fear.
In expanding bull structures, pullbacks create demand.
Tomorrow may become a test of whether this new wave of bulls is willing to buy the first meaningful AI pullback.